Insurance companies evaluate personal injury settlements by reviewing liability, injury-related losses, medical evidence, available coverage, and the likelihood that a dispute could lead to further negotiation or litigation. People researching insurance settlement information should remember that an average figure cannot account for the details that make one claim stronger, weaker, larger, or more limited than another. Whether the injury arose from a car crash, slip-and-fall, workplace incident, or another event, the central question is usually whether the available evidence supports the damages claimed. An insurer’s initial assessment is not necessarily the final value of a case, especially when treatment is ongoing or important facts remain disputed.
What Settlement Value Really Means
There is no universal formula for valuing a personal injury claim. The total damages associated with an injury may differ from the amount an insurer offers, and both may differ from the amount ultimately available under an insurance policy. A settlement evaluation commonly considers medical expenses, lost income, reduced earning capacity, pain and daily limitations, property damage when applicable, and reasonably expected future care. For example, two people may be involved in collisions that result in similar damage to their vehicles. One may recover after a brief course of treatment, while the other may need continuing care and miss substantial time from work. The visible damage to a vehicle is only one piece of the overall record.
The Main Factors That Shape a Claim
Adjusters generally examine the facts that affect responsibility, causation, and the scope of loss. The most important issues often include:
- How clearly another person or business can be shown to be at fault.
- The nature, severity, and duration of the injuries.
- The cost of past treatment and the support for anticipated future care.
- The effect of the injury on work, household tasks, mobility, and normal activities.
- The amount and type of insurance coverage available.
- Whether the injured person may share responsibility for the event.
- The consistency and quality of supporting records.
- Whether the medical condition has stabilized enough to assess future needs.
Evidence That Can Strengthen a Case
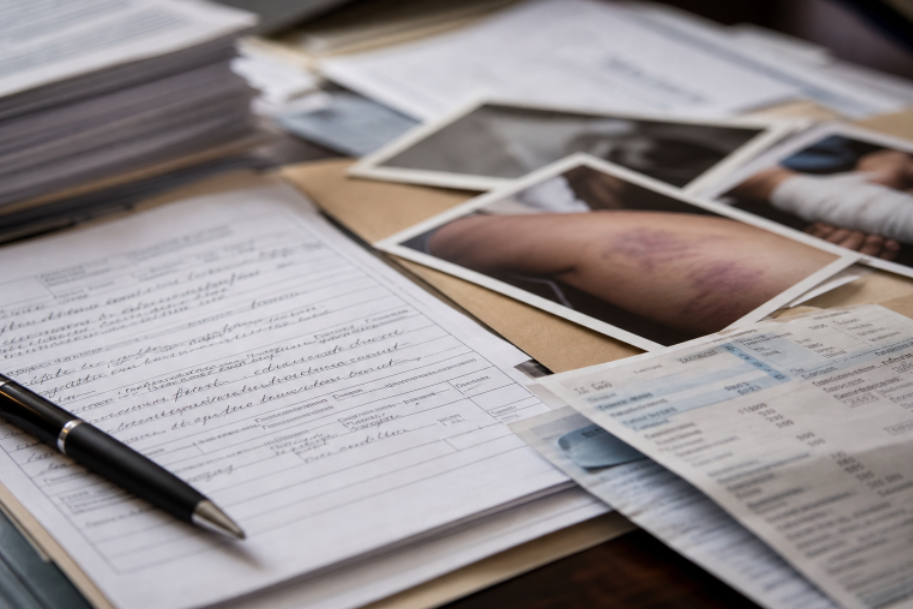
Early evidence can make it easier to address disagreements before memories fade or records disappear. Useful materials may include police or incident reports, scene photographs, videos, witness contact information, surveillance footage, repair estimates, medical bills, wage records, and notes describing symptoms and activity limits. Keeping original files, noting when each item was collected, and preserving complete rather than cropped images can help provide context. Social media posts also deserve care. A single photo of an activity may not show the pain, accommodations, or recovery time involved. However, it can still be used to challenge a claim if it appears inconsistent with reported limitations.
Why Medical Records Matter
Medical records help connect an event to the injuries and expenses claimed. Insurers may compare the timing of symptoms, examinations, diagnoses, imaging, treatment recommendations, and follow-up visits with the incident history. Clear communication with healthcare providers can help ensure records accurately reflect symptoms, functional limits, and treatment plans. Gaps in care may lead to questions about the severity or cause of an injury, but a gap does not automatically end a claim. Cost, transportation problems, work obligations, insurance issues, and delayed referrals can all affect treatment. Records may also distinguish between a diagnosed injury, patient-reported symptoms, objective test findings, and a provider’s recommendation for future care.
In many states, an injured person’s share of fault can reduce recoverable damages. Under comparative negligence principles, damages may be reduced by the percentage of responsibility assigned to the injured person. For instance, a $100,000 claim, reduced by 25 percent for fault, would result in $75,000 before considering coverage limits or other factors. The rules vary by state, and some jurisdictions apply stricter limits on recovery. This legal concept illustrates why fault arguments can have a major effect on settlement discussions. Common disputes involve speeding, distracted driving, unsafe lane changes, traffic conflict, failure to maintain property, failure to use available safety equipment, or actions that allegedly worsened an injury. The law of the state where the incident occurred controls, so general online guidance should not replace local legal advice.
How Insurance Policy Limits Affect Payment
An injury can be worth more than the liability coverage available to pay it. Auto policies, for example, may contain per-person and per-accident limits. A per-person limit generally caps what one injured claimant may receive under that coverage. In contrast, a per-accident limit applies to all covered injury claims arising from the same event. When several people are injured, they may seek payment under the same policy. Other potential sources can include uninsured or underinsured motorist coverage, medical payments coverage, commercial policies, employer coverage, or umbrella policies. Consumers can use the NAIC consumer page to locate state-based regulatory resources when concerns arise about an insurer.
Why Early Offers Need Careful Review
An insurer may make an early offer before the full medical outlook is known. A prompt offer is not automatically unfair, but accepting one usually requires signing a release that can end the right to pursue additional payment for the same claim. Before accepting, consider whether treatment has ended, future costs are known, property and injury damages are addressed separately, and medical liens or unpaid balances remain.
A Practical Settlement Negotiation Process
A well-organized claim often moves more efficiently because it gives the adjuster direct answers. A practical process includes gathering records, confirming coverage, calculating documented financial losses, reviewing the medical prognosis, preparing a clear demand, responding to disputed issues with evidence, and reviewing any release carefully before signing. For example, a demand that includes itemized bills, wage verification, relevant photographs, and a concise treatment timeline may reduce back-and-forth questions. It does not guarantee an agreement, but it can make the claim easier to evaluate on its actual merits.
Common Questions About Personal Injury Settlements
How Long Does a Personal Injury Settlement Take?
Timing depends on treatment, fault disputes, coverage questions, document collection, negotiations, and whether a lawsuit becomes necessary. Claims with unresolved medical issues often take longer because future losses may be difficult to evaluate early.
Should a Settlement Include Future Medical Costs?
Future care should be considered before a final release is signed when a provider expects additional treatment, therapy, procedures, or monitoring. The strength of this part of a claim depends on the medical support available.
Is a Lawyer Needed for Every Claim?
Not every minor claim requires legal representation. However, professional advice may be useful when injuries are serious, fault is disputed, multiple parties are involved, coverage is limited, or a release could affect substantial future rights.
Final Takeaway
Insurance companies do not evaluate personal injury settlements by relying on a single number. They may consider the available evidence, medical documentation, liability or fault, financial losses, insurance policy limits, treatment progress, and the timing of the claim. Medical records and bills can help document the nature and cost of treatment, while employment records and other financial documents may help establish lost income or related expenses. Evidence about how the injury affects daily activities, future treatment needs, and other nonfinancial losses may also be relevant, depending on the circumstances and applicable law. The insurer may also review photographs, accident reports, witness statements, and other information when assessing the claim. A careful review of the complete record can help an injured person understand which parts of the claim are supported by documentation, what information may still be missing, and which issues remain uncertain. Keeping organized records and resolving important questions before settlement can make it easier to evaluate whether an offer reflects the documented circumstances of the injury and its effects.
CLICK HERE FOR MORE BLOG POSTS
